Buying a Home · Grand County
Rates near 7% and plenty of inventory have handed second-home and luxury buyers something they have not had in years: time and leverage. Here are ten things to get right while you have them.
On September 24, 2026, Freddie Mac's weekly survey put the average 30-year fixed mortgage at 7.03%, up from 6.30% a year earlier. Here in the Fraser Valley, that has slowed the pace. When I pulled Flex MLS on September 30, there were 31 active 3-bedroom condos in Fraser and Winter Park against 38 sales over the previous 12 months, close to ten months of supply. The active listings had been on the market a median of 127 days.
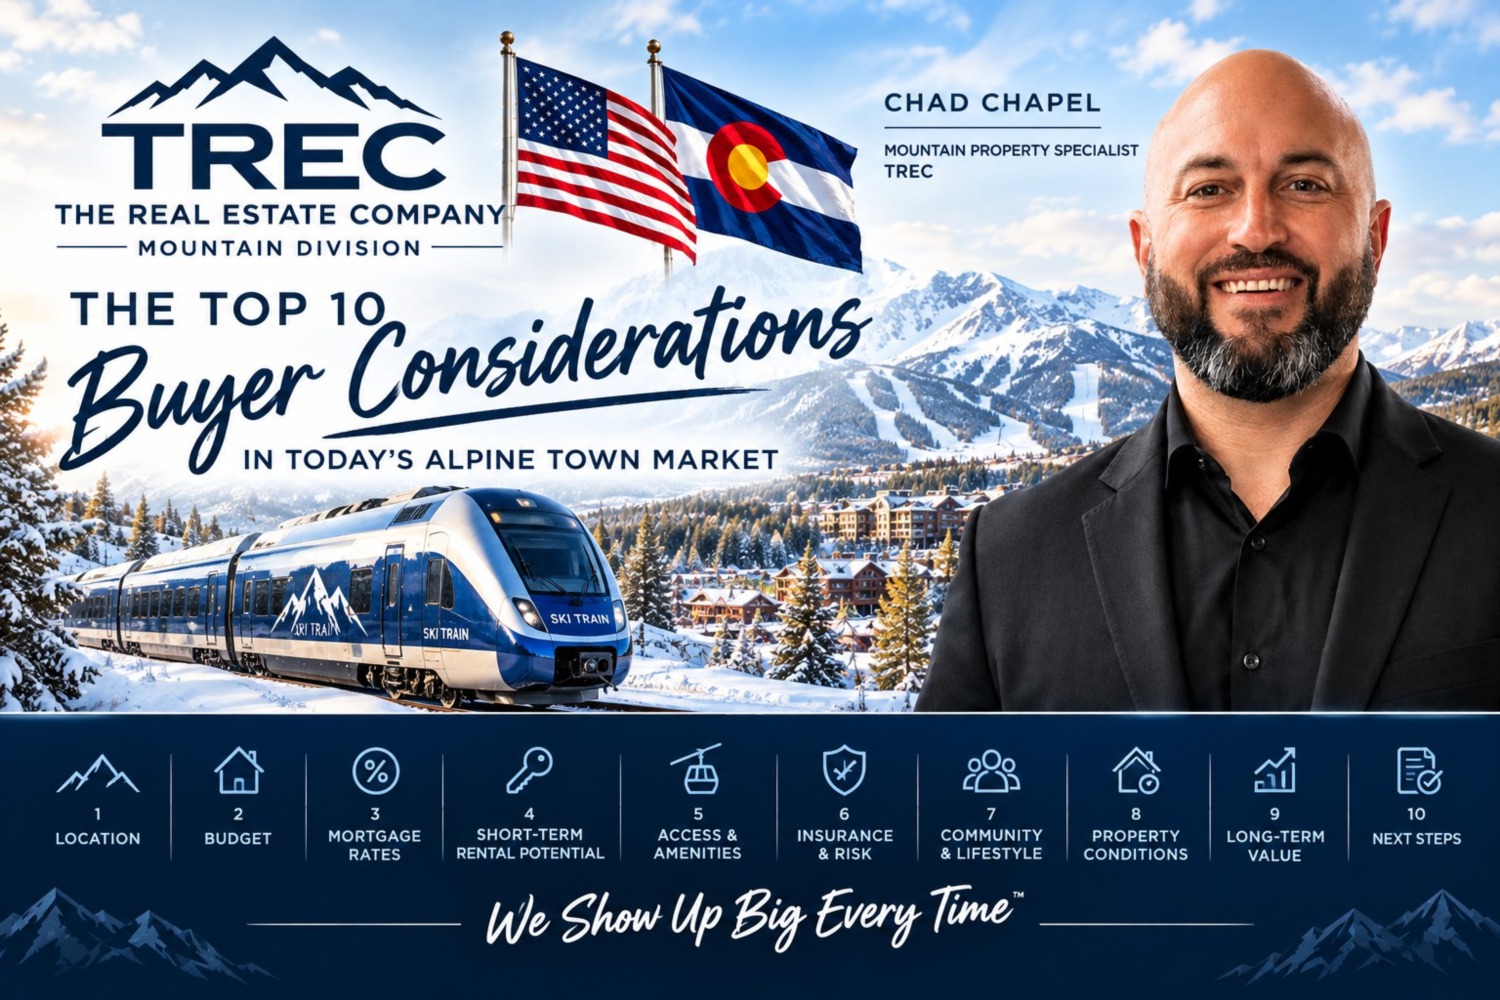
That is a buyer's market by almost any definition, and it rewards preparation more than speed. Whether you are shopping for a ski condo or a luxury home in Grand County, these are the ten considerations I walk every buyer through right now, each grounded in the rules that actually govern the deal.
Ten things to get right in this market
1. Finance it as a second home if that is how you will use it.
Lenders treat second homes and investment properties very differently. Fannie Mae's Selling Guide says a second home must be occupied by the borrower for some portion of the year, be suitable for year-round occupancy, and stay under the borrower's exclusive control. It also cannot be a rental property or a timeshare arrangement. Get the classification right up front, because it shapes your rate, your down payment and how much the seller can contribute.
2. Ask for seller concessions, and know the limits.
In a slower market, sellers are often more willing to pay toward your closing costs or a rate buydown than to cut the price. Fannie Mae caps those contributions on a second home at 3% of the price with less than 10% down, 6% with 10% to just under 25% down, and 9% with 25% or more down. On an investment property, the cap is 2% at any down payment. That gap alone is a reason to settle point one first.
3. Run the math on points before you pay them.
The Consumer Financial Protection Bureau explains that one discount point costs 1% of the loan amount and lowers your rate. Whether it is worth it depends on how long you will keep the loan. If you think you might refinance when rates drop, a seller-paid temporary buydown or a smaller permanent buydown may serve you better than a large one.
4. Lock your rate for the timeline you will actually need.
The CFPB notes that rate locks typically run 30, 45 or 60 days and can be expensive to extend. Mountain closings often run longer than city ones, between HOA document reviews, inspections in snow, and well or septic testing on rural homes. Ask your lender what an extension costs before you choose a lock period.
5. Know how rental income will be taxed.
The IRS has two rules every second-home buyer should know. Rent the home fewer than 15 days a year and you generally do not report that income at all. Use it personally for more than the greater of 14 days or 10% of the days it is rented, and the IRS treats it as a residence, which limits the rental expenses you can deduct. Talk with your CPA about how you plan to use the home before you buy it.
6. Check short-term rental rules town by town.
If rental income is part of your plan, confirm the rules where the property sits. Licensing, caps and waitlists differ across Winter Park, Fraser, Granby, Grand Lake and unincorporated Grand County, and an HOA can restrict rentals even where the town allows them. We covered this in detail in our post on why STR rules change at every town line.
7. Read the HOA documents like an owner, not a guest.
Many Fraser Valley condos and townhomes are in buildings from the 1970s and 1980s. Ask for the budget, the reserve study, recent minutes and any planned special assessments. A roof, siding or boiler project can mean thousands of dollars per unit, and the documents usually tell you it is coming long before the bill arrives.
8. Get an insurance quote before your inspection deadline.
Wildfire risk is reshaping mountain insurance. Colorado's statewide Wildfire Resiliency Code, created by Senate Bill 23-166, took effect July 1, 2025, and sets standards for building in the wildland-urban interface. For homes that cannot find standard coverage, the Colorado FAIR Plan describes itself as the state's last-resort option. Get a real quote early, while you can still renegotiate or walk away.
9. Plan for winter access and year-round living.
Fannie Mae requires a second home to be suitable for year-round occupancy, and in Grand County that means more than a furnace. Ask who plows the road, how steep the driveway is, and whether the home has reliable heat, water and internet in January. A home that is easy to reach in February is easier to enjoy, rent and eventually resell.
10. Price your offer to closed sales, and negotiate the terms too.
List prices tell you what sellers hope for. Closed sales tell you what buyers paid. In a market with long days on market, use recent closings as your anchor, then negotiate the full package: price, concessions, inspection repairs, furniture and closing date. The best deals this year are often won on terms, not just price.
A buyer's market rewards the prepared buyer. The leverage is real, but only if you know which levers to pull.
If you are selling, the same list works for you
Every item above is also a roadmap for sellers. Buyers who are focused on monthly payments will respond to a seller-paid buydown, so price your home to recent closed sales and consider offering concessions within the lender limits instead of waiting for price reductions. Have your HOA documents, rental history and recent insurance information ready, because a buyer who can answer their own questions quickly is a buyer who keeps moving toward closing.
Above all, make the home easy to say yes to. A clean inspection, clear winter access and a well-documented rental record help a listing stand out among the many homes buyers can choose from right now.
Rates and markets move in cycles. Buyers who use this stretch well can secure the right property on better terms than they will likely see when the market tightens again. The work is in the details, and that is where a local team earns its keep.
If you would like help working through these ten points on a specific property, whether you are buying or selling, I am glad to sit down with you.
Chad Chapel
Mountain Property Specialist
The Real Estate Company -- Mountain Division · Winter Park, Colorado
MOBILE 970-363-9770 · OFFICE 970-426-5500
trecwp.com · View Chad's profile
Sources
Freddie Mac Primary Mortgage Market Survey, September 24, 2026 · Flex MLS, Grand County, 3-bedroom condominiums in Fraser and Winter Park, pulled September 30, 2026 · Fannie Mae Selling Guide B2-1.1-01, Occupancy Types · Fannie Mae Selling Guide B3-4.1-02, Interested Party Contributions · CFPB, Discount points and lender credits · CFPB, Rate locks · IRS Topic 415, Renting residential and vacation property · Colorado Division of Fire Prevention and Control, Wildfire Resiliency Code · Colorado FAIR Plan