The Real Estate Company – Mountain Division Winter Park, Colorado | trecwp.com
Buying a Home in Winter Park, Colorado
Why You're Never "Locked In" Once You Go Under Contract
Introduction
If you're considering buying a home in Winter Park, Colorado, there's a good chance one thought keeps circling back: what if I change my mind after I go under contract? It's one of the most common questions we hear from buyers, whether they're purchasing a primary residence, a second home near Winter Park Resort, or an investment property they plan to rent out during ski season.
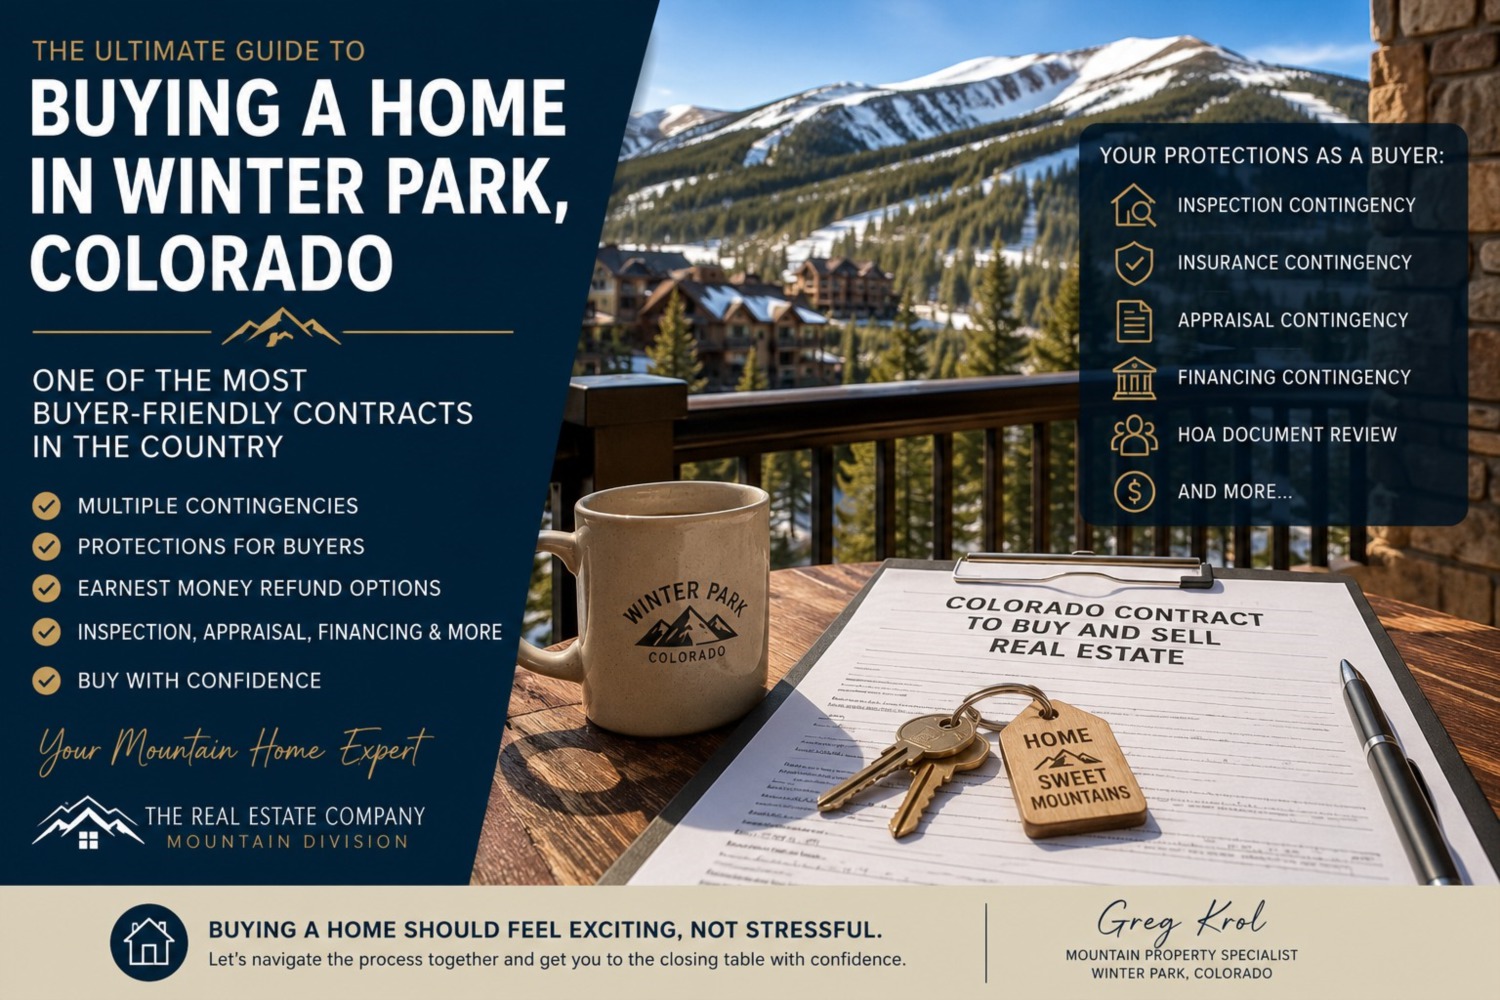
Here's the short answer: going under contract in Colorado does not mean you're locked into buying the home. The Colorado Contract to Buy and Sell Real Estate is built around a series of contractual off-ramps — inspection, appraisal, financing, insurance, HOA review, and title — each with its own deadline and its own path back to your earnest money. Understanding how these contingencies work is the difference between feeling anxious about writing an offer and feeling confident about it.
This guide walks through exactly how the process works, from earnest money to closing day, with examples specific to Winter Park, Fraser, Tabernash, Granby, and the rest of Grand County. As always, this article is educational in nature and is not a substitute for legal advice — you'll want to review your specific contract deadlines with your Realtor and lender.
Why Buyers Are Often Nervous to Make an Offer
Buying a home is one of the largest financial decisions most people will make, and mountain properties come with their own layer of complexity — snow loads, HOA structures, well and septic systems, and insurance markets that behave differently than they do along the Front Range. It's natural for buyers to worry that submitting an offer commits them irreversibly to the purchase.
In reality, most of that fear comes from unfamiliarity with the contract itself, not from the contract's actual terms. Colorado's standard purchase contract was designed with buyer protection in mind, and once you understand the sequence of contingencies, the process starts to feel a lot less like a leap of faith and more like a structured, step-by-step evaluation period.
Why Colorado Is Considered One of the Most Buyer-Friendly States for Residential Real Estate Contracts
Quick answer: Colorado's Contract to Buy and Sell Real Estate gives buyers multiple, separately-timed contingencies — inspection, appraisal, financing, insurance, HOA, and title — each of which allows the buyer to terminate and receive their earnest money back if it's not resolved to their satisfaction, provided they act by the deadline.
Unlike some states where a buyer might have only one general "due diligence period," Colorado breaks the process into distinct objection and resolution deadlines. Each contingency exists independently, which means a problem with, say, homeowners insurance doesn't have to be bundled into the inspection period. This layered structure is one of the main reasons real estate professionals across the state — including buyers relocating from more restrictive markets — consistently point to Colorado's contract as one of the more balanced, buyer-protective documents in the country.
What Happens After My Offer Is Accepted?
Quick answer: Once your offer is accepted, the contract dates begin running immediately — typically starting with earnest money delivery, followed by inspection, appraisal, loan, title, and HOA deadlines. Your Realtor will provide a deadline calendar so you know exactly what's due and when.
Going under contract kicks off a defined timeline rather than a final commitment. In a typical Winter Park or Grand County transaction, your Realtor will walk you through a personalized calendar showing every deadline — inspection objection, inspection resolution, appraisal, loan conditions, and title review — so nothing catches you off guard. Missing a deadline can mean losing the right to object, which is why working closely with an experienced local agent matters, particularly for properties in HOA communities like Rendezvous, Pole Creek, or Meadow Ridge, where document review can take a little extra time.
How Earnest Money Works in Colorado
How Much Earnest Money Do I Need?
Quick answer: Earnest money in Colorado is negotiable, but it's typically around 1–3% of the purchase price. In competitive mountain markets like Winter Park and Fraser, buyers sometimes offer a higher amount to strengthen their offer, though the amount itself doesn't change your contingency rights.
Earnest money is a good-faith deposit that shows the seller you're serious about the purchase. It's held by a title company or brokerage, not by the seller directly, and it's applied toward your down payment and closing costs at closing.
When Does Earnest Money Become Refundable?
Quick answer: Earnest money remains refundable any time you terminate the contract in writing within one of your active contingency periods — inspection, appraisal, loan, insurance, HOA, or title — by the applicable deadline.
Do Buyers Lose Earnest Money in Colorado?
Quick answer: Buyers only risk losing earnest money if they miss a deadline to object or terminate, or if they terminate outside of an active contingency without a contractual basis to do so. As long as you and your Realtor track deadlines carefully, earnest money stays protected.
This is where having a local Realtor who actively manages your deadline calendar becomes so valuable — especially on mountain properties where inspections, HOA document requests, or insurance quotes can take a few extra days compared to a Denver metro transaction.
The Inspection Objection: Your Biggest Layer of Protection
Can I Cancel During Inspection?
Quick answer: Yes. During the inspection period, you can negotiate repairs or credits (Inspection Resolution), or you can terminate the contract entirely and receive your earnest money back (Inspection Termination) — all without needing the seller's agreement.
The inspection period is often the contingency buyers find most reassuring, because it gives you the broadest reason to walk away. A licensed inspector will evaluate the home from foundation to roofline, and in a mountain environment like Grand County, a few areas deserve extra attention:
- Structural concerns and foundation issues — mountain homes experience freeze-thaw cycles that can affect foundations over time, particularly in older cabins around Fraser and Tabernash.
- Roof condition and snow load — heavy annual snowfall near Winter Park Resort means roofs need to be evaluated for age, material, and ability to handle snow load, along with any ice-damming history.
- Electrical and plumbing systems — especially in older second homes that may have been winterized and unoccupied for stretches of time.
- Heating systems — a functioning, well-maintained furnace or boiler is essential for high-altitude Colorado winters.
- Radon — like much of Colorado, Grand County has areas with elevated radon potential, so testing is worth including in your inspection scope.
- Well and septic systems — common in Tabernash and more rural parts of Granby, wells and septic systems warrant their own specialized inspection.
- Mold and environmental concerns — moisture intrusion from snowmelt or older insulation can be a factor worth checking, particularly in properties that sit vacant part of the year.
If anything turns up that you're not comfortable with, you have the right to ask the seller for repairs or a credit (Inspection Resolution) or simply terminate and get your earnest money back (Inspection Termination) — all within your inspection deadline.
The HOA Contingency: One of the Most Important Reviews You'll Do
How Does the HOA Contingency Work?
Quick answer: If the property is part of an HOA, you have the right to review governing documents, financials, and meeting minutes, then terminate the contract if you're not comfortable with what you find — a critical step for many Winter Park and Grand County condos and townhomes.
A large share of homes for sale in Winter Park, Fraser, and surrounding communities — including Hi Country Haus, Beaver Village, Base Village, and Lakota — are part of an HOA. Reviewing the HOA package thoroughly is one of the most valuable things you can do as a buyer, because it tells you how the community is actually run day to day. Items worth examining closely include:
- Rules and regulations, including short-term rental policies (important for anyone considering a vacation rental investment)
- Financial statements and budget health, to understand whether the association is financially stable
- Reserve study and reserve funding, which indicate whether the HOA is prepared for major future repairs
- Working capital contributions due at closing
- Pending litigation involving the association
- Insurance coverage carried by the HOA itself
- Rental restrictions and pet restrictions
- Architectural guidelines, which matter if you're planning renovations
- Special assessments, current or anticipated
- Property management quality and responsiveness
Because HOA documents can take time to review, especially for larger communities, this is one of the deadlines your Realtor will want to track closely from the very start of your transaction.
The Insurance Objection: A Uniquely Mountain Concern
What If I Can't Get Insurance?
Quick answer: Colorado's contract includes an insurance contingency that allows buyers to terminate if they're unable to secure a homeowners insurance policy on acceptable terms — an increasingly important protection in wildfire-prone mountain areas.
Insurance availability has become a bigger conversation in mountain real estate over the past several years. Wildfire risk, higher premiums, and, in some cases, non-renewals have made it essential for buyers to get an insurance quote early in the process rather than waiting until closing week. This is particularly true for properties in forested areas around Grand County or homes near Rocky Mountain National Park's boundary. If you're unable to obtain coverage you're comfortable with by your insurance deadline, you have the right to terminate and keep your earnest money.
The Appraisal Contingency
What If the Appraisal Comes In Low?
Quick answer: If the appraised value comes in below the contract price, you generally have options: renegotiate the price with the seller, bring additional cash to closing to cover the gap, or terminate the contract under the appraisal contingency and receive your earnest money back.
Appraisal outcomes can vary in resort markets where comparable sales are limited or where recent renovations aren't fully reflected in nearby comps — something that comes up from time to time in smaller communities like Tabernash or Grand Lake. If your appraisal comes in low, you're not without options, and it's worth having a conversation with your lender and Realtor about which path makes the most sense for your situation.
The Loan (Financing) Objection
What Happens If Financing Falls Through?
Quick answer: The loan contingency protects buyers who are unable to secure final loan approval — whether due to interest rate changes, employment verification issues, or credit changes — allowing termination and return of earnest money within the loan deadline.
Financing a mountain second home can differ slightly from financing a primary residence, since lenders sometimes apply different guidelines to non-owner-occupied or seasonal properties. Staying in close communication with your lender throughout underwriting — and understanding your loan deadline — is one of the best ways to protect yourself during this stage.
Title Review, Survey, and Mineral Rights
Colorado buyers also have the right to review the title commitment for the property, which can reveal easements, boundary issues, or mineral rights considerations — a topic that comes up more often in Colorado than in many other states given the state's mining history. A survey can help confirm boundary lines, particularly useful for larger parcels near Granby Ranch or the more rural stretches of Grand County. If a title defect is discovered, buyers have a contractual path to address it before closing.
Seller Property Disclosures
Sellers in Colorado are required to complete a Seller's Property Disclosure, detailing known issues such as past repairs, water intrusion, roof history, and the condition of mechanical systems. This document is a valuable companion to your own inspection, giving you the seller's first-hand knowledge of the home's history alongside your inspector's professional assessment.
The Final Walk-Through
Shortly before closing, buyers complete a final walk-through to confirm the property is in the agreed-upon condition, that any negotiated repairs were completed, and that the home is ready for you to take possession. This is your last checkpoint before closing day, and it's worth taking your time with it.
Closing Day: Wire Fraud Awareness, Keys, and Moving In
Closing day is exciting, but it's also a moment to stay alert to wire fraud. Always confirm wiring instructions by phone with your title company using a verified number — never rely solely on emailed instructions, which can be spoofed. Once funds are confirmed and documents are signed, you'll receive your keys, and your Winter Park home is officially yours.
Buying in Grand County: Winter Park, Fraser, Tabernash & Granby
Every mountain town in Grand County has its own personality. Winter Park offers proximity to Winter Park Resort and an active vacation rental market. Fraser, sitting along the Fraser River, tends to attract buyers looking for a slightly quieter residential feel. Tabernash offers larger acreage properties, often with well and septic systems. Granby, near Granby Ranch and closer to Rocky Mountain National Park and Grand Lake, appeals to buyers who want a bit more space and access to year-round recreation.
Across communities like Rendezvous, Pole Creek, Lakota, Meadow Ridge, Hi Country Haus, Beaver Village, and Base Village, buyers will find a mix of condos, townhomes, and single-family homes — many with HOAs that are worth reviewing carefully, as outlined above. Whether you're drawn to golf at Pole Creek Golf Club, the trails near Devil's Thumb Ranch, winter programs through the YMCA of the Rockies, or simply the drive up over Berthoud Pass, Grand County offers a lifestyle that's hard to replicate.
Let's Find Your Mountain Home
Buying a home in Winter Park or anywhere in Grand County should feel exciting — not stressful. Colorado's buyer-friendly contract gives you real, contractual room to evaluate the property, the HOA, the insurance market, and your financing before you're ever truly committed. As your local Mountain Property Specialist, I'm here to walk you through every inspection, every deadline, and every contingency so you can move forward with confidence.
If you're considering buying a home in Winter Park, Fraser, Tabernash, Granby, or anywhere in Grand County, let's talk. Reach out any time — I'd love to help you find the right mountain property and guide you through every step of the process.
Greg Krol Mountain Property Specialist - 720-703-3114
The Real Estate Company – Mountain Division
Winter Park, Colorado | trecwp.com This article is for general educational purposes only and does not constitute legal advice. Buyers should review all contract deadlines and contingencies with their Realtor, and financing details with their lender.